Pre-construction due-diligence report
Oceana · 1BR — Punta Cana
1BR / 1BA · 84 m² · $149,000 · Independent analysis of a pre-construction purchase approaching delivery
Sample report · Analysis as of October 2026 · Prepared by SRealtyNest
01Executive summary
Verdict: PROCEED WITH CONDITIONS — Deal score 68 / 100
A below-market entry price ($1,774/m² vs. $2,000–$2,500 Punta Cana / Bávaro benchmark, midpoint $2,250) plus positive financed cash flow (+$497/mo at Scotiabank's 8.50% five-year fixed, ~+$576/mo during the fixed period before the assumed 10.50% reset). This deal cash-flows under leverage from day one — DSCR 1.69, 7.5% cash-on-cash, 9.8% cap rate — which is uncommon for DR pre-construction at current rates. The price is fixed: no ICDV or construction-cost escalation clause. A professional operator is in place: Yurbban Hospitality Group proposes an 18% all-in pool fee (vs. the 25% generic assumption), which is the single biggest driver of the improved carry. The gating item is legal: zero of six diligence checks are verified — title, permits, CONFOTUR, contract clauses, fiduciary structure, and HOA regime all require independent attorney review before closing. Key conditions: verify the legal chain before closing, confirm the 51% pool-participation threshold is met before operations launch, and underwrite occupancy at 50% rather than 60%.
Deal score
68 / 100
price 30 · carry 19 · break-even 19 · checks 0
Entry price
$1,774 / m²
benchmark $2,000–$2,500
Net cash flow
+$497 / mo
Scotiabank 8.50% × 5yr → 10.50%, 20 yr
Flip @ $208.6K
+$15.1K
3.7% annualized · tied with renting
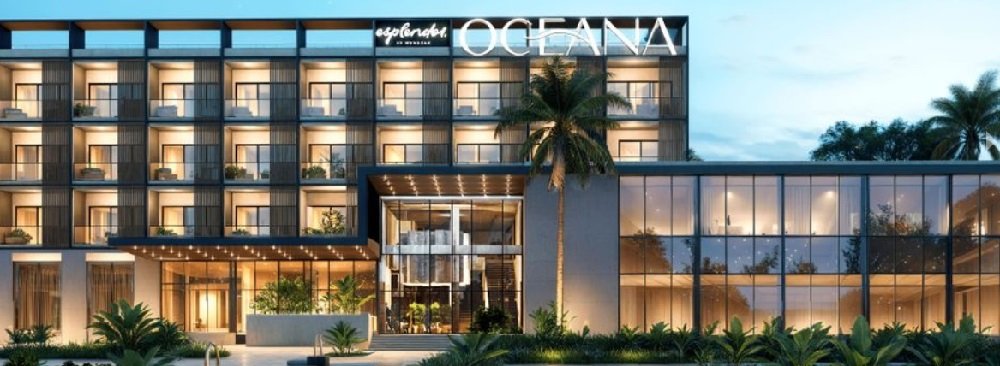
Oceana is a 1-bedroom, 1-bathroom unit (84 m²) in Bávaro, Punta Cana, developed by Noval Properties. Purchased pre-construction at a fixed $149,000 price with $74,500 paid to date (50%); $74,500 to finance at delivery, expected Q1 2027. The buyer's plan is to mortgage the balance in USD — Scotiabank's 8.50% five-year fixed is the preferred structure — and operate the unit as a short-term rental.
The math is unusually balanced. As a rental, the deal works under leverage: $2,160/mo gross rent (ADR $120 × 60% occupancy) against a $647/mo mortgage payment for five years (~$726 after the assumed 10.50% reset) leaves +$576/mo during the fixed period (~+$497/mo post-reset) after Yurbban's 18% pool fee, HOA, insurance, utilities, and 5% reserves — 7.5% cash-on-cash on $79,000 cash to close. As a flip, reselling at the $208,600 market value nets ~$15,100 after 5% selling costs and 10% capital-gains tax — but that is essentially tied with holding and renting for 24 months (+$14,900 rent-path gain). The flip only wins decisively above ~$230,000. This is a hold-and-rent deal unless the market runs.
02Property profile
| Attribute | Detail |
|---|---|
| Unit | 1BR beachfront (sample) |
| Layout | 1 bedroom / 1 bathroom |
| Interior area | 84 m² |
| Project | Oceana, Bávaro — Punta Cana |
| Purchase price | $149,000 — $1,774/m² (fixed, no escalation clause) |
| Purchase terms | Pre-construction; 50% paid to date |
| Developer | Noval Properties (Wyndham partnership) |
| Delivery | Contractual Apr 2024 → end 2025 (Noval est.) → projected Q1 2027 (~35-mo delay; see §08) |
Punta Cana / Bávaro is the country's primary tourism pole — the highest hotel occupancy, the largest airport gateway, and the deepest short-term-rental market in the Dominican Republic. The 1BR format is the most liquid segment for investor-buyers: lower ticket, broader resale pool. At $1,774/m² the entry sits ~21% below the $2,250 benchmark midpoint — the margin of safety this deal is built on.
03Purchase structure & financing
| Item | Amount |
|---|---|
| Purchase price (fixed) | $149,000 |
| Paid to date (50%) | $74,500 |
| Balance to finance | $74,500 |
| Estimated closing costs (~3%) | $4,500 |
| Total cash to close | $79,000 |
Financing scenarios (USD mortgage, 20-year amortization)
| Lender / structure | Rate | Monthly P&I | Note |
|---|---|---|---|
| Scotiabank — 5-yr fixed → reset ★ | 8.50% → 10.50% | $647 → ~$726 | Preferred: lowest 5-yr cost; get the revision formula in writing |
| LAFISE — fixed for life | 10.50% | $744 | Certainty anchor; no reset risk |
| BHD — 1-yr fixed → reset | 7.75% → 10.50% | $612 → ~$739 | Lowest first-year payment; rate locks at approval, not application |
| Cash (no mortgage) | — | $0 | Best cash flow; ties up $74.5K |
Appraisal & loan-to-value
| Item | Amount |
|---|---|
| Appraised value (est.) | $208,600 |
| Max loan (80% LTV) | $166,880 |
| Amount to finance | $74,500 |
| Resulting LTV | 36% |
Teaser-rate trap
Several banks advertise 6.50–8.25% 'starting' rates fixed for 12 months. The post-fixed revision formula is routinely undisclosed — including on the preferred Scotiabank 8.50% structure, whose post-year-5 rate is an underwriting assumption, not a quote. A 1-year teaser at 8% that resets to 12% costs more over 5 years than 10.50% fixed for life. Never sign without the revision clause in writing.
04Short-term rental analysis
Gross rent
$2,160 / mo
ADR $120 × 60% occ.
Net cash flow
+$497 / mo
after all costs + mortgage (post-reset)
Cash-on-cash
7.5%
on $79,000 cash to close
Cap rate
9.8%
NOI $14,676 ÷ $149,000
| Monthly P&L | Amount |
|---|---|
| Gross rental income (ADR $120 × 60% × 30 days) | $2,160 |
| Management — Yurbban pool (18%) | -$389 |
| HOA | -$150 |
| Insurance | -$190 |
| Utilities + internet | -$100 |
| Maintenance reserve (5%) | -$108 |
| Mortgage P&I — Scotiabank (post-reset 10.50%) | -$726 |
| Net cash flow | +$497 |
The rental case is the strength of this deal: it cash-flows under leverage from day one, which is uncommon for DR pre-construction at current rates. DSCR of 1.69 means net operating income covers the mortgage payment 1.69× — comfortably inside the bank's comfort zone. Break-even occupancy is 43%: the unit can sit empty more than half the month and still cover every cost including the mortgage. The 18% Yurbban pool fee (vs. a generic 25% assumption) adds ~$150/mo directly to net cash flow — operator selection is the highest-leverage variable in this underwriting.
What 50% occupancy looks like
At 50% occupancy, gross drops to $1,800/mo and net to +$220/mo — still positive, at 3.3% cash-on-cash. The deal survives a 10-point occupancy miss. Below 43% it goes negative. Underwrite 50%, hope for 60%.
Operator: Yurbban Hospitality Group
Yurbban Hospitality Group (est. 2012, Barcelona) operates 24 assets and 1,514 rooms across the US, Europe, and Latin America. Its Oceana proposal uses a pool model: all participating units run as a single hotel operation, with net income distributed proportionally to each owner's investment — lower volatility than independent STR, at the cost of control.
| Fee component | Rate |
|---|---|
| Management fee | 8.0% |
| Marketing | 1.4% |
| Incentive fee | 1.4% |
| Sales channels | 1.4% |
| Total operator load | ~18% |
Yurbban's stabilized Year-5 projection targets 79% occupancy at $204 ADR with 9.0% ROI and a 37% net margin — materially above this report's 60% / $120 base case, which is deliberately conservative for a new listing ramping over 6–12 months. Treat 79% as upside, not the plan.
Pool terms to verify before signing
The pool requires 51% of owners to participate before operations launch — if the threshold isn't met, there is no hotel operation and no rental income. Owners get 90 days/year of personal use (summer blackouts apply). Exit is constrained: you can sell, but the buyer must stay in the pool, and independent short-term rental outside the pool is not permitted. A 1–5% FF&E/CapEx reserve applies, plus an initial working-capital contribution (quoted at $6,807 for the $269K typology — confirm the figure for this unit). Open question: Yurbban's smallest listed typology is priced at $269,000 (Junior Suite Boulevard) against this unit's $149,000 purchase price — reconcile which typology and pool coefficient applies to this unit before signing.
05Flip / exit analysis
Net profit @ $208.6K
+$15,142
after costs + 10% gains tax
Annualized ROI
3.7%
over 44-mo capital lockup
Break-even resale
$190,786
zero-profit; rent gains +$14.9K
Rent-vs-flip
Tied
flip +$248 over 24-mo hold
| Resale price | Net profit | Annualized ROI |
|---|---|---|
| $190,786 (zero-profit) | $0 | 0.0% |
| $208,308 (rent parity) | +$14,894 | 3.7% |
| $208,600 (market value) | +$15,142 | 3.7% |
| $230,000 (+54%) | +$33,332 | 7.8% |
The flip case is honest about its limits: at the $208,600 market value, flipping nets $15,142 — just $248 more than holding and renting for the same 24 months. There is no meaningful flip premium at current market pricing; the flip only compensates for the 44-month capital lockup above ~$230,000. The critical sensitivity is delay — each additional 6 months of developer delay shaves roughly 0.4 points off the annualized return without changing nominal profit, because capital sits at 0% during the slip. Note the track record: contractual April 2024 → end of 2025 (Noval's own estimate, missed) → Q1 2027, ~35 months behind — the forward lockup in this analysis (14 months construction + 6 months delay + 24 months hold) assumes no further slippage beyond the 6-month underwriting. Underwrite 12 months of delay as the stress case, not 6.
06Market analysis — Punta Cana & Bávaro
Price benchmarks
| Benchmark | Figure | Source / date |
|---|---|---|
| Punta Cana / Bávaro condo ($/m²) | $2,000–$2,500 | International Property Directory, 2026 |
| This deal | $149,000 ($1,774/m²) | Contract (fixed price) |
At $1,774/m² the entry sits below the benchmark range — a genuine pre-construction discount in the country's priciest condo market. Punta Cana commands its premium on sustained international demand, and the discount is the margin of safety: even flat prices from here leave the zero-profit resale at $190,786, only 28% above the purchase price.
Tourism demand
The Dominican Republic received 9.24 million visitors in Jan–Sep 2026 (+7.5% YoY), with the tourism minister projecting 12.4M+ for the full year — another national record. Punta Cana's airport handles the majority of arrivals: it is the country's primary tourism gateway, and Bávaro's beach corridor is its densest hotel and short-term-rental zone. Demand is not the risk in this market.
Short-term rental market
Punta Cana / Bávaro has the deepest short-term-rental market in the country — the largest listing pool and the most professionalized management infrastructure. That depth cuts both ways: proven demand, but also the most competitive supply. The 60% occupancy assumption sits above typical 40–50% underwriting; it must be stress-tested, not taken as given. New listings typically ramp over 6–12 months, and professional management plus launch pricing decide which side of the median a unit lands on.
Market read
Record national tourism, the country's deepest STR market, and a below-benchmark entry price support the investment thesis. The 60% occupancy assumption is the variable to stress — underwrite 50%, and the deal still cash-flows. Execution and reviews will decide whether this unit beats the median.
07Developer due diligence — Noval Properties
Noval Properties is one of the Dominican Republic's larger developers, with branded hotel partnerships (Wyndham, Archipelago) — a step above the small regional builders that dominate pre-construction. Scale, however, has not meant smooth delivery: buyer forums document years of delays and poor communication at The Reef in Las Terrenas (the company attributed roughly 2.5 years to an environmental permit), and 2025 brought defamation suits against critics. For Oceana specifically, one buyer reported a ~6-month slip with construction progressing. Read the record correctly: institutional scale with a documented history of timeline overruns — underwrite delay, not just price.
| Check | Finding | Status |
|---|---|---|
| Corporate standing | Large developer; Wyndham / Archipelago partnerships | Pass |
| Buyer complaints / litigation | Documented delays at The Reef (Las Terrenas); defamation suits vs. critics (2025) | Flag |
| Delivery track record | Oceana buyer-reported ~6-mo slip; Q1 2027 delivery per developer | Monitor |
| Price escalation | Fixed $149,000 — no ICDV clause | Pass |
Delay is the base case
Noval's history says to underwrite 12 months of delay, not 6. Each additional 6 months shaves roughly 0.4 points off the flip's annualized return without changing nominal profit, because capital sits at 0% during the slip. The rental case is unaffected by delay until delivery — but the buyer's capital stays locked.
08Legal, tax & compliance
| Item | Status | Note |
|---|---|---|
| Title path | Pending | Requires independent title study (estudio de títulos) before closing |
| Fiduciary / trust structure | Pending | Verify whether buyer funds sit in a regulated fiduciary trust; confirm registration before the mortgage disburses |
| Construction permits | Pending | Municipal permits not yet verified |
| CONFOTUR certification | Pending | Not verified for this project/unit — if certified, 15-year transfer-tax & IPI exemption would apply |
| Purchase contract clauses | Partial | Art. 9 (delivery date) and Art. 14 (0.5%/mo delay penalty — gross-negligence standard; Noval claims force majeure) reviewed — see delivery clause below. Refund and buyer-default clauses not yet reviewed — request the full promesa de compraventa |
| HOA regime | Pending | Condo regime documents and budget not yet reviewed |
Delivery clause (Art. 9) — reviewed
The contract commits the developer to deliver the unit no later than April 2024. The delivery estimate has slipped twice since: end of 2025 (Noval's written estimate in 2025), now Q1 2027 — roughly 35 months behind the contractual date, with each revised date itself missed. Article 9 lists force majeure events that suspend the delivery term: earthquakes or cyclones (suspension for the duration plus reconstruction time), wars, riots, rebellions, armed conflict, and shortages of materials or equipment (extended by the number of days not worked). Buyer late payment on any installment also extends the delivery date. Noval attributes the delays to force majeure: Hurricane Fiona's impact in September 2022, permitting delays following the death of the Minister of Environment and Natural Resources, and imported-material supply-chain disruptions. These are Noval's characterizations, communicated in a 2025 email from its post-sales department — not independently verified findings.
Two terms are notably buyer-unfriendly. Rain: isolated rainy days that make site work impossible are added to the delivery date 1:1 — but three or more continuous days of rain are multiplied by two or three times, and the product is added to the delivery date. The developer has no obligation to notify the buyer when rain extensions apply. On penalties: Article 14 does provide a 0.5% monthly penalty on amounts delivered — but only for delay caused by the developer's gross negligence. Noval has classified all delays to date as justified force majeure, declaring the penalty inapplicable. The penalty exists on paper, but invoking it requires the buyer to prove gross negligence against the developer's unilateral force majeure determination — a bar that, in practice, leaves the buyer with no working remedy while capital sits at 0%.
Three missed dates — 35 months behind contract
April 2024 (contract) → end of 2025 (Noval's 2025 estimate) → Q1 2027 (current projection). Each revised delivery date was missed. Confirm the revised date in writing, ask which force majeure triggers the developer considers still active, and underwrite further slippage — the Art. 14 penalty requires proving gross negligence, which Noval's standing force majeure classification makes practically unreachable.
This is the report's gating item: zero of six checks are verified. The financial case is sound, but no money should move at closing until an independent DR attorney confirms title, permits, and contract terms. Budget $500–$1,500 for legal review — the cheapest insurance in this transaction. Transfer tax is 3% of assessed value (~$4,470 at purchase price — the basis for the $4,500 closing estimate above); annual property tax (IPI, Law 18-88) is $0 at this price point, below the ~$167,000 exempt threshold.
09Risk register
| Risk | Likelihood | Impact | Mitigation |
|---|---|---|---|
| Construction delay (Noval track record) | High | Medium | Underwritten 6 mo; stress 12 mo. Extends the 0%-return lockup; rental case unaffected until delivery. |
| Extended delivery delay (35+ months behind contract) | High | Medium | Three missed dates: Apr 2024 → end 2025 → Q1 2027. Art. 14 penalty (0.5%/mo) requires proving gross negligence; Noval classifies all delays as force majeure, making it practically unreachable. Confirm revised delivery in writing; underwrite further slippage. |
| Pool launch threshold (51% participation) | Medium | High | No hotel operation — and no rental income — until 51% of owners join the pool. Confirm current sign-up count before closing. |
| Operator typology / price gap | Medium | Medium | Yurbban's smallest listed typology is $269K vs. this unit's $149K purchase price. Reconcile the applicable pool coefficient and fee base in writing. |
| Occupancy below 60% | Medium | High | 43% is break-even; 50% still cash-flows +$220/mo. Professional operator + launch pricing; ramp over 6–12 months. |
| Unverified legal chain | Medium | High | Independent attorney review of title, permits, CONFOTUR, and contract before closing — non-negotiable. |
| Resale liquidity (1BR) | Low | Low | 1BR is the most liquid investor segment in Punta Cana; market-value exit available at $208.6K. |
| HOA / special assessments | Low | Medium | Review condo budget at delivery; 5% maintenance reserve in underwriting. |
Get this report for your unit
Independent financial diligence before you wire money — delivered in 2–5 business days.
By proceeding to payment, you agree to our Terms of Service, Privacy Policy, Payments & Refunds, and acknowledge that SRealtyNest provides informational research only, not legal or financial advice.
Sources & methodology
- •SRealtyNest Deal Scorecard — Oceana 1BR scenario (score 68; +$497/mo net; 9.8% cap; zero-profit resale $190,786)
- •Yurbban Hospitality Group — Oceana operator proposal & profitability analysis (pool model, ~18% all-in fee, 79% Year-5 occupancy target, 9.0% ROI) — owner-provided Feb 2025 / May 2026, reference only
- •International Property Directory — Punta Cana / Bávaro condo benchmark ($2,000–$2,500/m²), 2026
- •Caribbean Journal — DR welcomed 9.2M visitors Jan–Sep 2026; 12.4M projected
- •DRListings — Dominican Republic mortgages for foreigners (USD 8–10%; 30–50% down for non-residents)
- •TheLatinvestor — Foreigner mortgage eligibility & rates, 2026
- •Owner-provided: purchase terms ($149,000 fixed price, $74,500 paid / 50%, contractual Apr 2024 → end-2025 → Q1 2027 delivery), Art. 9 (delivery) & Art. 14 (0.5%/mo penalty) contract text shared in chat, Noval post-sales email 2025 (Cristopher López) on delay causes and penalty inapplicability, Yurbban Hospitality Group profitability analysis (Feb 2025), lender quotes (Scotiabank 8.50% × 5yr preferred, LAFISE 10.50% fixed-for-life, BHD 7.75%) — observed Oct 2026, reference only
Disclosures
- This is a sample report provided for illustration of the SRealtyNest due-diligence product. It is based on a combination of owner-provided figures, public listing data, and third-party market datasets. It is not a personalized recommendation.
- Nothing in this report constitutes financial, investment, legal, or tax advice. Real estate investment involves risk, including possible loss of capital. Consult a licensed attorney in the Dominican Republic and qualified advisors in your home jurisdiction before making investment decisions.
- Market figures are drawn from the sources listed below, believed to be reliable but not guaranteed. Data is as of the dates stated; market conditions change. Verify all material facts independently.
- Financial projections (rental income, occupancy, appreciation, flip returns) are hypothetical illustrations based on stated assumptions, not guarantees of future performance. Past market performance does not predict future results.
- SRealtyNest is not a brokerage, bank, law firm, or tax advisor, and has no affiliation with, or endorsement from, any developer, lender, or data provider named in this report. Rate quotes are observed market data for reference, not offers of credit.
- Currency is USD unless otherwise noted. Dominican-peso figures use approximate 2026 exchange references and are for illustration only.
Prepared by SRealtyNest · For questions about a full due-diligence report on your own deal, see srealtynest.com.